On 11 December 2025, the National Assembly passed the Law on Investment No. 143/2025/QH15 (“Investment Law 2025”), which took effect on 1 March 2026 and replaces the Law on Investment No. 61/2020/QH14. This marks a significant update to the legal framework governing investment activities in Vietnam.

However, as the implementing regulations guiding the Investment Law 2025 have not yet been fully issued to facilitate the application of new investment procedures, on 4 March 2026, the Ministry of Finance issued Official Letter No. 2519/BTC-PC to provide guidance on the implementation of the Investment Law 2025, ensuring continuity in state administration and the handling of administrative procedures in the investment sector without disruption.

Accordingly, the provisions under Decree No. 31/2021/ND-CP guiding the Law on Investment and Decree No. 19/2025/ND-CP on special investment procedures will continue to apply during the transitional period until the official implementing regulations of the Investment Law 2025 are promulgated. In addition, existing guiding circulars (including Circular No. 03/2021/TT-BKHĐT) will remain in effect.

To ensure continuity in the receipt and processing of investment dossiers, the Ministry of Finance requests competent authorities, as well as enterprises and investors, to continue applying the procedures and processes under the aforementioned existing regulations. This approach helps minimize legal gaps and avoid practical difficulties during implementation.

Official Letter 2519/BTC-PC reflects a clear “soft transition” approach adopted by the regulatory authorities in the course of reforming the investment legal framework. In this context, enterprises and investors should take note of the following key points:

  • Continue applying the current investment regulations under Decree No. 31/2021/ND-CP, Decree No. 19/2025/ND-CP, and relevant circulars until the implementing regulations for the Investment Law 2025 are issued;
  • Proactively monitor forthcoming implementing regulations of the Investment Law 2025 to promptly update and adjust investment activities, thereby mitigating compliance risks once the new rules take effect;

Assess the priority and timing of planned investment projects to determine whether to proceed with investment registration under the current framework or defer until the new implementing regulations on investment procedures are issued.

On 4 March 2026, the General Department of Taxation issued Official Letter No. 1296/CT-NVT (“Official Letter 1296”), providing detailed guidance on the declaration and finalization of personal income tax (“PIT”) for income derived from salaries and wages for the 2025 tax period, while also updating certain provisions applicable from the 2026 tax period. Key highlights include the following:

Personal deductions for income from salaries and wages

Effective from the 2026 tax period, the personal deduction threshold is increased from VND 11 million/month (equivalent to VND 132 million/year) to VND 15.5 million/month (equivalent to VND 186 million/year) for taxpayers, and from VND 4.4 million/month to VND 6.2 million/month for each dependent. This adjustment raises the non-taxable income threshold and reduces the tax burden on individuals.

Tax rates applicable to income from salaries and wages

For the 2025 tax finalization, resident individuals’ income from salaries and wages remains subject to the progressive tax tariff comprising seven brackets, with rates ranging from 5% (for taxable income up to VND 60 million/year) to 35% (for taxable income exceeding VND 960 million/year).

From the 2026 tax period, this tariff will be streamlined to five brackets, with the 5% rate applicable to taxable income up to VND 120 million/year, and the highest rate of 35% applicable to taxable income exceeding VND 1.2 billion/year.

Scope and subjects required to conduct PIT finalization

Official Letter 1296 clarifies the scope and subjects required to conduct PIT finalization. Income-paying organizations and individuals are responsible for declaring and finalizing PIT, including conducting finalization on behalf of individuals where valid authorization is provided.

For individuals, direct finalization obligations arise in cases such as: having income from multiple sources without meeting authorization conditions; foreign employees terminating their employment in Vietnam; or individuals receiving income from foreign entities, international organizations, or diplomatic missions where PIT has not been withheld during the year.

The Official Letter also specifies cases where PIT finalization is not required, including where no income is paid, business operations are suspended during the calendar year, or where the additional tax payable after finalization does not exceed VND 50,000, as well as cases where excess tax has been paid but the taxpayer does not request a refund or offset.

Authorization for PIT finalization

Official Letter 1296 further clarifies the circumstances under which individuals may authorize PIT finalization. Typically, this applies to individuals who have labor contracts of three months or more with a single employer and are still employed at the time of finalization; or those who earn additional irregular income from other sources not exceeding VND 10 million/month on average, which has already been subject to 10% withholding.

Conversely, individuals with multiple income sources, those with additional tax payable or refundable amounts, or specific cases such as foreign employees terminating employment in Vietnam, should assess whether they are required to directly finalize PIT with the tax authorities.

Online tools supporting PIT finalization

To facilitate taxpayers, the tax authorities have deployed various systems supporting electronic declaration and submission.

For income-paying organizations: software such as the Tax Declaration Support (HTKK) version 5.5.8, iTaxViewer version 2.6.3, and the tax authority’s administrative procedure processing system are used for declaration and submission of finalization dossiers.

For individuals: digital platforms such as the tax authority’s public service portal, the eTax Mobile application, and the National Public Service Portal support declaration, submission, and tracking of dossier status.

Automatic PIT refund mechanism for individuals

A notable development is the implementation of an automatic PIT refund mechanism for individuals conducting direct finalization. From 2025 onwards, taxpayers may submit refund dossiers electronically, and where the dossier satisfies all prescribed conditions, the system will automatically process the refund within approximately three working days. Official Letter 1296 also specifies the applicable conditions and provides guidance on required documentation and system functionalities.

Overall, Official Letter 1296 enhances the efficiency of tax administration, ensuring transparency and consistency in PIT finalization while reducing administrative burdens through increased digitalization. Accordingly, ALIAT recommends that enterprises:

  • Proactively review employees’ authorization documents for PIT finalization;
  • Identify cases where employees are required to directly finalize PIT with tax authorities;

Verify the proper withholding and issuance of tax withholding certificates.

On 23 January 2026, the Government promulgated Decree No. 37/2026/ND-CP detailing a number of provisions and measures for the implementation of the Law on Product and Goods Quality (“Decree 37”). Decree 37 will take effect from 1 July 2026. Its key highlights are summarized as follows:

Risk-Based Product and Goods Quality Management

Under previous regulations, products and goods were classified into 02 groups: (i) goods not capable of causing safety risks; and (ii) goods potentially capable of causing harm to human health, animals, plants, and the environment.

Under Decree 37, products and goods are classified into 03 risk levels in terms of their impact on human health, animals, plants, and the environment, namely: low risk, medium risk, and high risk.

The risk level of goods is determined based on an assessment of factors such as: (i) the severity of impact; (ii) the ability to control, mitigate, or eliminate hazards in practice and the capacity for recovery after impact; (iii) the scale of impact; and (iv) the frequency of occurrence during actual use. The determination of these factors must be grounded in scientific evidence and practical data, as well as the regulatory capacity and management requirements of competent state authorities from time to time.

For this purpose, Decree 37 also sets out detailed technical criteria and scoring methodologies for assessing the risk levels of products and goods. The lists of products and goods classified as medium-risk and high-risk (together with their corresponding HS codes under the Import and Export Tariff Schedule) will be issued by the relevant regulatory authorities in the near future, with an implementation roadmap commencing from 1 July 2026.

The risk-based classification of goods serves as the basis for determining which information must be displayed on physical labels and which information may be integrated into electronic labels. Simultaneously, the shift to risk-based classification of goods means that regulatory and labeling obligations will no longer apply uniformly but will instead vary depending on the risk level of each product. This may directly affect both the scope of information required to be disclosed and the corresponding management approach.

Introduction of Extensive New Labelling Requirements

Decree 37 expands labeling obligations in the context of e-commerce. Sellers are required to publicly disclose complete label information when trading on digital platforms (except for certain batch-specific details such as date of manufacture or batch number). E-commerce platform operators are required to ensure transparent display of information and to facilitate connectivity with state management data systems where necessary.

In addition, whereas previous regulations focused primarily on physical labels, Decree 37 introduces a legal framework for electronic labeling. Certain mandatory information may now be presented through QR codes, RFID technology, or other electronic data carriers, rather than being limited to traditional physical labels. The formal recognition of electronic labels enables enterprises to digitalize product information, while also facilitating traceability and integration with state management databases.

Furthermore, Decree 37 revises the rules on label placement in a more practical manner. Labels must be affixed in a location that is easily visible and allows all required information to be read without disassembling product components. Mandatory labeling content is not required to be concentrated in a single location, provided that it remains complete and readily identifiable. This approach affords enterprises greater flexibility in packaging design, while simultaneously imposing higher standards regarding information visibility and accessibility.

The recognition of electronic labeling and the expansion of labeling requirements to the e-commerce environment indicate that product information is no longer managed through a single format (i.e., physical labels), but must instead be administered concurrently across multiple interfaces (including physical labels, electronic labels, and e-commerce platforms). This not only requires enterprises to ensure the accessibility and proper display of information in practice, but also to maintain the completeness and consistency of such information across all formats.

In addition, the more flexible rules on label placement and presentation provide enterprises with greater flexibility in packaging design, while at the same time imposing higher requirements in terms of visibility and accessibility of information, particularly where content is presented in a dispersed manner or integrated through electronic means.

Application of Technology Platforms in Quality Management and Traceability

Decree 37 introduces specific provisions on the development and implementation of technology platforms to support product and goods quality management.

With respect to digital applications in data collection, storage and sharing, Decree 37 encourages manufacturers and traders to adopt coding systems in various forms, including one-dimensional barcodes, two-dimensional codes (QR codes, DataMatrix), radio-frequency identification (RFID), near-field communication (NFC), and other appropriate technological solutions.

Priority is also given to integrating advanced technologies such as Artificial Intelligence (AI), Big Data, and the Internet of Things (IoT) to ensure seamless data collection, management, storage and sharing throughout the entire supply chain.

Decree 37 further encourages the use of barcodes and identification codes for quality management and product traceability. Traceability systems implemented by organizations and individuals must ensure full traceability of the entire formation and circulation process of products in accordance with applicable national, international, regional, foreign or corporate standards, consistent with the law on standards and technical regulations.

Such systems must be declared as conforming to applicable standards; where a corresponding national technical regulation exists, a declaration of conformity must be made in accordance with regulations.

Minimum traceability data required within the system include: Product name and image; Name and address of the manufacturing/trading organization or individual; Origin; Brand/trademark; Batch number, lot number or serial number (if any); Expiry date (if any).

The Ministry of Science and Technology is the unified authority responsible for nationwide traceability management, including: promulgating and publishing standards and technical regulations; ensuring data connectivity and sharing systems; operating, maintaining and upgrading the National Product and Goods Traceability Portal and the national platform for identification, authentication and traceability; and managing traceability codes and data carriers.

Provincial-level People’s Committees are responsible for organizing and coordinating traceability inspections within their localities in collaboration with relevant ministries and agencies.

The above changes introduced under Decree 37 reflect a broader shift in the approach to managing product and goods quality, thereby giving rise to significant implications for enterprises’ compliance obligations and operational activities. Specifically:

In the short term, enterprises may incur increased costs associated with reviewing product classification systems, adjusting label and packaging designs, and investing in technological infrastructure to support electronic labeling and product traceability. At the same time, ensuring consistency and completeness of product information across multiple forms of presentation will also increase internal governance and compliance requirements.

Nevertheless, in the long term, the adoption of electronic labeling and traceability systems may enable enterprises to optimize product management, enhance transparency, and thereby improve market trust and support business operations, particularly in the digital environment.

Accordingly, ALIAT recommends that enterprises focus on the following:

  • Proactively monitor, update and review product lists by risk classification once guidance from competent authorities is issued;
  • Review labelling practices, including electronic labels and e-commerce disclosures, to: (a) ensuring that product labels are placed in a position that is easily visible and allow all mandatory information to be fully readable without the need to disassemble the product; (b) ensuring the visibility and completeness of mandatory information, including where such information is presented in a dispersed manner; and (c) ensuring consistency and alignment between physical labels, electronic labels, and information disclosed on e-commerce platforms;
  • proactively reviewing and classifying goods and packaging in accordance with the transitional provisions of Decree 37, whereby: (a) for product labels and packaging printed prior to 01 July 2026, a plan should be developed for their continued use or replacement within a maximum period of two (02) years from 01 July 2026; and (b) for goods that have been manufactured, imported, or already placed into circulation prior to this date, such goods may continue to be circulated until their expiry date.

Reviewing and assessing the necessity of upgrading technical infrastructure to support the implementation of electronic labeling and product traceability, including product coding systems, data storage and management systems, as well as the capability to connect and share information with relevant governmental data management platforms.
On 12 February 2026, the Ministry of Health issued Circular No. 03/2026/TT-BYT (“Circular 03”), effective from 15 February 2026, abolishing a number of regulations in the healthcare sector. Notably, it removes the requirements relating to the issuance of the Cosmetic Advertising Content Approval Certificate (previously stipulated under Circular No. 09/2015/TT-BYT). Accordingly, all requirements concerning dossiers, procedures, and processes for obtaining approval of cosmetic advertising content have ceased to be effective as of the effective date of Circular 03. This change clearly reflects a regulatory shift from a pre-approval regime to a post-market surveillance mechanism in the management of cosmetic advertising activities, with notable implications for enterprises as follows:

Change in regulatory approach and increased burden of compliance substantiation

The abolition of the advertising content approval procedure marks a fundamental shift in the regulatory approach—from pre-publication control to post-publication supervision. This significantly reduces administrative burdens, enabling enterprises to shorten marketing timelines and enhance business flexibility. However, the removal of the prior approval mechanism also means that enterprises are now required to self-assess and assume full responsibility for the legality of their advertising content.

While Circular 03 simplifies administrative procedures, it simultaneously increases the burden on enterprises to demonstrate compliance. In the event of inspections or audits, enterprises must be prepared to provide complete product declaration dossiers, supporting documents substantiating advertising claims, and evidence of internal control processes.

Increased requirements for internal control and standardization of advertising content

Despite the removal of administrative procedures, substantive regulations governing cosmetic advertising content remain fully applicable under relevant laws. Advertising content must include essential information such as product name, features, functions, and details of the entity responsible for placing the product on the market, and must be consistent with the product declaration dossier.

Importantly, cosmetic advertisements must not mislead consumers into believing that the product is a medicinal product or has therapeutic effects. The use of images or endorsements by healthcare institutions or medical professionals is restricted. Furthermore, product claims must align with the nature of the product and applicable principles, including those under the ASEAN Cosmetic framework, to avoid exaggeration or misrepresentation.

In this context, enterprises must go beyond formal content checks and establish systematic internal control mechanisms to ensure that all advertising content is legally and technically substantiated. Compliance is no longer solely the responsibility of the legal department but requires close coordination between legal and marketing functions throughout the content development process.

Overall, Circular 03 represents a clear transition from a pre-approval to a post-market supervision regime in cosmetic advertising management. While this change facilitates business operations, it also significantly increases the level of self-compliance responsibility and legal risk exposure. Accordingly, compliance should now be approached as a proactive and continuous internal control system rather than reliance on prior regulatory approvals.

In light of the above changes, enterprises are advised to adopt a proactive and systematic compliance approach:

  • Conduct a comprehensive review of all existing advertising content and cross-check it against product declaration dossiers to identify high-risk elements, particularly claims relating to efficacy and functions;
  • Establish an internal advertising content review and approval process with clearly defined roles for legal and marketing teams, applying specific review criteria prior to publication;
  • Strengthen control over third parties through contractual arrangements, approval mechanisms, and monitoring processes to mitigate risks arising from the broader advertising ecosystem;
  • Develop and maintain a documentation system for advertising content and supporting materials to facilitate inspections and regulatory inquiries, while also implementing internal training programs to enhance compliance awareness across relevant departments.

On 31 March 2026, the Government promulgated Decree No. 103/2026/ND-CP (“Decree 103”) guiding outbound investment activities, which took effect on 3 April 2026. Decree 103 is designed to streamline administrative procedures for outbound investment and encourage investment activities. Notable provisions include the following:

Classification of Investment Procedures Based on Capital Scale

Under the previous regulations, there was no exemption from the requirement to obtain an Outward Investment Registration Certificate (OIRC), meaning all outbound investment projects, regardless of capital size, were subject to registration procedures, thereby creating administrative burdens.

Under Decree 103, the requirement to obtain an OIRC is classified based on capital scale as follows:

  • Projects with investment capital of less than VND 7 billion are exempt from the OIRC requirement (only foreign exchange registration is required);
  • Projects with investment capital from VND 7 billion to less than VND 1,600 billion, or projects in sectors subject to conditional outbound investment, require the Ministry of Finance to issue the OIRC;
  • Projects with investment capital of VND 1,600 billion or more must obtain approval from the Prime Minister.

For enterprises and investors, these new provisions are expected to shorten investment timelines for small-scale projects that are exempt from the OIRC requirement, enabling faster implementation and timely capture of business opportunities; reduce compliance costs through streamlined procedures, documentation, translation, notarization, and legal advisory expenses; and facilitate market testing through small-scale exploratory investments with reduced financial exposure.

From a regulatory perspective, the new framework reflects a shift from ex-ante approval to ex-post supervision, reducing initial licensing requirements while strengthening monitoring during project implementation. At the same time, it enhances the role of banks in managing capital flows through foreign exchange registration, thereby maintaining control over outbound foreign currency movements.

Recognition of Share Swap Mechanism

Decree 103 formally recognizes that Vietnamese investors may use shares, capital contributions, or profits to conduct outbound investment through share swap arrangements, subject to the following four principles:

  • Completion of outbound investment procedures in advance (if applicable);
  • Shares used in the swap must be valued on a market basis and comply with tax and anti-transfer pricing regulations;
  • Foreign investors receiving Vietnamese shares must complete investment procedures in accordance with applicable laws; and
  • Share swap arrangements must not be used for transfer pricing, tax evasion, or money laundering purposes.

This mechanism expands available investment structures, enabling enterprises to undertake cross-border M&A or restructuring without relying entirely on cash payments. It also enhances transaction flexibility, as the use of shares, capital interests, or projects facilitates valuation negotiations and deal structuring, particularly within multinational corporate groups. In addition, share swaps can help mobilize resources and reduce immediate cash flow pressures, thereby easing financial burdens at the time of transaction.

Digitalization and Integration of National Data Systems in Investment Procedures

Under Decree 103, enterprises are required to submit outbound investment dossiers electronically, with procedures integrated into the national investment data system. The system enables automatic cross-checking of enterprise registration data, tax records, and foreign exchange information. Any discrepancies between declared information and existing databases may be immediately identified.

This digitalization policy is expected to shorten processing timelines, as electronic submissions allow for faster receipt, circulation, and feedback compared to traditional paper-based processes. Data connectivity also facilitates automatic verification against enterprise, tax, and foreign exchange records, reducing duplication of information submission.

At the same time, conducting outbound investment procedures electronically enhances transparency and accountability, thereby improving the effectiveness of state management.

In addition, when filing corporate income tax finalization returns, enterprises are required to concurrently prepare reports on the establishment and utilization of science and technology development funds in accordance with applicable regulations.

Conditions for Outbound Investment by Economic Organizations with Majority Foreign Ownership

Decree 103 introduces additional requirements for economic organizations in which foreign investors hold more than 50% of charter capital when conducting outbound investment, including:

  • Only equity capital may be used for outbound investment;
  • The organization must have recorded profits for two consecutive years (based on audited financial statements);
  • Where retained earnings are used for outbound investment, the following sequence must be followed: issuance of the OIRC → capital increase and full contribution of charter capital in Vietnam → remittance of investment capital abroad.

These requirements—particularly the prohibition on using borrowed capital and the requirement of two consecutive years of profitability—set relatively stringent standards for outbound investors. In practice, such conditions may exclude startups, innovative enterprises, or high-growth companies. Failure to meet the profitability threshold may limit access to international investment opportunities and reduce the competitiveness of Vietnamese enterprises in regional and global markets.

Repatriation of Profits to Vietnam

Decree 103 introduces a new principle on profit repatriation, requiring investors to remit all profits and other income derived from overseas investment activities back to Vietnam within 12 months from the date of profit distribution.

This requirement may lack flexibility for industries with long investment cycles—such as infrastructure, energy, agriculture, technology, or market expansion—which often require reinvestment of profits. The 12-month deadline may not align with actual business cycles. Additionally, the fixed timeframe may expose investors to foreign exchange risks if funds must be converted and remitted during unfavorable exchange rate conditions, particularly for large profit amounts. Applying a uniform repatriation timeline across all investment types may not adequately reflect differences in capital needs, profitability cycles, and operational models across sectors.

Overall, Decree 103 establishes a new legal framework that simplifies administrative procedures, diversifies investment structures, and strengthens digitalization in the management of outbound investment activities. These changes are expected to shorten project implementation timelines, reduce compliance costs, and expand structuring options for enterprises.

However, Decree 103 also imposes stricter requirements on financial conditions, funding sources, and profit repatriation obligations, thereby requiring enterprises to undertake careful legal, financial, and compliance planning. Accordingly, businesses should consider the following actions:

  • Review the capital scale of each outbound investment project to determine the applicable procedural requirements (exemption or approval), thereby optimizing implementation timelines and compliance costs;
  • Develop phased investment strategies, leveraging the exemption mechanism for small-scale projects to test markets before scaling up;
  • When applying share swap mechanisms, ensure compliance with market-based valuation, tax regulations, anti-transfer pricing rules, and completion of all relevant investment procedures to mitigate legal risks;
  • Standardize internal data (enterprise registration, tax, foreign exchange) and ensure consistency of information prior to electronic submission to avoid rejection or delays due to discrepancies;
  • For economic organizations with foreign ownership exceeding 50%, assess compliance with equity funding requirements and the two-year profitability condition, and develop appropriate financial plans for outbound investment; and

Establish cash flow planning and profit repatriation strategies aligned with the 12-month deadline, while taking into account exchange rate fluctuations and reinvestment needs in the host market

On 12 March 2026, the Ministry of Finance issued Circular No. 20/2026/TT-BTC (“Circular 20”), providing detailed guidance on certain provisions of the Law on Corporate Income Tax and Decree No. 320/2025/ND-CP on the implementation of the Law on Corporate Income Tax. Circular 20 introduces several notable points as follows:

Detailed guidance on supporting documents for deductible expenses

Circular 20 provides more detailed and stringent requirements regarding the documents and supporting evidence required for expenses to qualify as deductible for corporate income tax (“CIT”) purposes, including the following additional requirements:

Expenses for vocational education and employee training: Enterprises must maintain a financial regulation governing training expenses; decisions on employee nomination for training; employee training registration dossiers; and diplomas/certificates evidencing training results.

Expenses incurred by employees on behalf of the enterprise: For expenses of VND 5 million or more where employees are authorized to procure goods/services for business purposes and payments are made via non-cash methods, the enterprise must have: valid invoices and supporting documents; internal regulations/financial policies/decisions authorizing such employee payments; proof of non-cash payment made by the employee; and proof of reimbursement made by the enterprise to the employee via non-cash payment.

Registration of investment capital for expansion projects with tax authorities

For enterprises with registered investment projects, where there is any change in the investment capital for the purpose of expanding an investment project, a written notification must be submitted to the directly managing tax authority at the same time as the submission of the annual CIT finalization return, and no later than the year in which the expansion project is implemented.

During the implementation of the expansion project, if there are further adjustments to the registered investment capital, the enterprise must notify the tax authority accordingly.

Inclusion of assets formed from the Science and Technology Development Fund as deductible expenses

Circular 20 expands the categories of assets eligible for inclusion as deductible expenses. Specifically, where fixed assets are formed from the Science and Technology Development Fund for scientific research and technological development activities, and such assets (which have not been fully depreciated) are subsequently transferred for use in production and business activities, the remaining value of such fixed assets shall be recorded as other income and be depreciated and included as deductible expenses for CIT purposes.

Timing for determining taxable revenue for foreign enterprises

Circular 20 provides specific guidance on the timing for determining taxable revenue for foreign enterprises in certain cases:

Capital transfer activities: The timing is the date on which the capital transfer agreement becomes effective in accordance with applicable laws.

Securities transfers (including certificates of deposit): The timing is the date on which the transfer transaction is executed.

Derivative securities transfers (futures contracts): The timing is either (i) when the buy/sell order is matched on the stock exchange trading system, or (ii) when the futures contract reaches its settlement/maturity date.

Overall, Circular 20 restructures the approach to declaration, substantiation, and management of CIT-related expenses, while expanding the scope of deductible assets and clarifying the timing for revenue recognition in specific cases. This enhances the ability of tax authorities to more closely monitor and enforce CIT obligations, while also providing enterprises with clearer procedural guidance for tax declaration and finalization. In light of these developments, ALIAT recommends that enterprises:

  • Proactively monitor, update, and review expense items to ensure proper classification of deductible expenses for CIT purposes;
  • Review and supplement supporting documentation for deductible expenses to ensure compliance with the new requirements;
  • In cases of investment project expansion, ensure timely notification to tax authorities regarding changes in investment capital;
  • For foreign enterprises engaging in capital transfers, securities transactions, or derivative securities transactions, carefully determine and record the appropriate timing for recognizing taxable revenue for CIT purposes.

On 31 March 2026, the Government promulgated Decree No. 96/2026/ND-CP detailing and guiding the implementation of several provisions of the Law on Investment 2025 (“Decree 96”). Decree 96 takes effect from 31 March 2026, except for Articles 11 and 12, which will take effect from 1 July 2026, and replaces Decree No. 31/2021/ND-CP, Decree No. 19/2025/ND-CP, and Decree No. 239/2025/ND-CP. Key highlights focus on streamlining investment procedures, selectively expanding investment incentives, decentralizing approval authority, and introducing more flexible market entry mechanisms for foreign investors in Vietnam.

Special Investment Procedures – a “Green Lane” Mechanism for Eligible Projects

For the first time, Decree 96 introduces a “special investment procedure” applicable to certain projects implemented in industrial parks, export processing zones, high-tech parks, concentrated digital technology zones, free trade zones, international financial centers, and functional zones within economic zones. Under this mechanism, eligible projects may be exempted from procedures such as investment policy approval, detailed environmental impact assessment (EIA), construction permits, and the preparation of detailed 1/500 planning. The timeline for issuance of the Investment Registration Certificate (IRC) is shortened to a maximum of 15 working days and is centrally handled by the management authority of the relevant industrial park/economic zone or other competent authority.

This mechanism may significantly reduce the legal preparation timeline for projects, particularly in sectors with short product life cycles such as semiconductors, electronics, data centers, and high technology. However, simplified procedures do not equate to reduced compliance obligations. Investors must commit to full compliance with national technical regulations on construction, environmental protection, and fire prevention and fighting; prepare their own techno-economic reports; and notify the competent authority at least 30 days prior to the intended commencement date. Accordingly, the new mechanism shifts regulatory focus from ex-ante approval to ex-post supervision, thereby increasing the importance of robust internal compliance controls from the early stages of project development.

Expanded and More Targeted Investment Incentives

Decree 96 refines investment incentive policies to focus on high value-added sectors, innovation, and strategic technologies, including semiconductors (R&D, design, manufacturing, packaging, and testing), AI/cloud data centers, 5G infrastructure, green hydrogen, green ammonia, and other key technology industries. Notably, Decree 96 introduces specific capital thresholds and disbursement requirements for each category of project, ensuring that only projects with substantial capital commitment and genuine implementation qualify for incentives.

In addition to corporate income tax incentives of up to 1.5 times the standard level, eligible projects may also receive financial support from the Investment Support Fund and, in certain cases, assistance with foreign currency balancing. However, enterprises must ensure ongoing compliance with all eligibility conditions, particularly those relating to business sectors, capital scale, disbursement progress, technology transfer, localization ratios, and the participation of Vietnamese enterprises in the supply chain.

Updates on Market Access Conditions and Decentralization of Investment Authority

Decree 96 maintains the list of sectors subject to market access restrictions for foreign investors, including sectors not yet open to market access and those subject to conditional access. Importantly, it supplements regulations concerning the management and operation of intermediary e-commerce platforms, social networks engaged in e-commerce activities, and integrated e-commerce platforms, reflecting a trend toward tighter regulatory oversight of digital business models.

At the same time, Decree 96 revises the decentralization framework for investment policy approval by narrowing the authority of the Prime Minister and expanding that of provincial-level People’s Committee Chairpersons. This decentralization may shorten project approval timelines and enhance local autonomy. However, variations in appraisal capacity and administrative practices across provinces may lead to inconsistencies, delays, or divergent documentation requirements.

More Flexible Market Entry Models for Foreign Investors

A notable new development is that foreign investors may establish an economic organization prior to obtaining an Investment Registration Certificate (IRC), and subsequently apply for the IRC for their project. This approach allows investors to obtain legal entity status at an early stage to open bank accounts, enter into lease agreements, recruit personnel, and undertake initial preparatory activities. However, the IRC must be obtained within 12 months from the date of establishment.

Given the absence of clear legal consequences in cases where the IRC is not granted within this timeframe, contracts entered into during the interim period should be carefully structured, particularly with respect to conditions precedent, termination rights, refund mechanisms, and risk allocation.

Overall, Decree 96 reflects a significant reform in Vietnam’s investment regime, facilitating investor entry while shifting part of the regulatory burden toward post-licensing supervision. In light of this, ALIAT recommends that enterprises focus on the following:

  • Proactively monitor, update, and review expense items to ensure proper classification of deductible expenses for CIT purposes;
  • Review and supplement supporting documentation for deductible expenses to ensure compliance with the new requirements;
  • In cases of investment project expansion, ensure timely notification to tax authorities regarding changes in investment capital;
  • For foreign enterprises engaging in capital transfers, securities transactions, or derivative securities transactions, carefully determine and record the appropriate timing for recognizing taxable revenue for CIT purposes.

In order to provide detailed guidance on tax declaration and payment for household businesses (“HBs”) and individual businesses (“IBs”), the Government has issued Decree No. 68/2026/ND-CP on tax policies and tax administration applicable to these entities (“Decree 68”), effective from 5 March 2026.

Increase in taxable revenue threshold

One notable point under Decree 68 is the introduction of an annual revenue threshold of VND 500 million as the basis for determining tax obligations. Accordingly, HBs and IBs with annual revenue of VND 500 million or less are not subject to value-added tax (“VAT”) and personal income tax (“PIT”). Conversely, where revenue exceeds this threshold, HBs and IBs must fulfill their tax obligations in accordance with applicable regulations.

Tax calculation methods

For PIT purposes, Decree 68 provides for two (02) tax calculation methods. Specifically, the method of applying a deemed tax rate on taxable revenue applies to HBs and IBs with annual revenue exceeding VND 500 million up to VND 3 billion. Meanwhile, the method based on taxable income multiplied by the applicable tax rate applies to HBs and IBs with annual revenue exceeding VND 3 billion, as well as those with revenue from over VND 500 million up to VND 3 billion that opt to apply this method. Under the latter method, PIT is determined based on taxable income, i.e., revenue after deducting expenses related to business activities during the tax period.

Increased application of e-invoices

In addition to changes in tax calculation methods, Decree 68 strengthens tax administration through the application of e-invoices. Accordingly, HBs with annual revenue of VND 1 billion or more, or those whose VAT taxable revenue in the preceding year is below VND 1 billion but reaches VND 1 billion or more during the tax year, are required to use e-invoices bearing tax authority authentication codes or e-invoices generated from cash registers connected to the tax authority’s system. For those with annual revenue from over VND 500 million to below VND 1 billion, the use of e-invoices is encouraged depending on business needs.

Declaration of bank accounts used for business activities

Another new requirement under Decree 68 is that, from 5 March 2026, HBs and IBs must proactively declare to the tax authorities the bank accounts and e-wallets used for their business activities. This requirement aims to enhance transparency in revenue recognition and the management of cash flows arising from business operations. In practice, for ease of declaration, reconciliation, and tax administration, HBs and IBs should separate accounts used for business activities from those used for personal purposes.

Overall, Decree 68 represents a significant shift in the tax administration mechanism for HBs and IBs, marking a transition from a presumptive tax regime to a system based on actual revenue and e-invoice data. The establishment of the VND 500 million revenue threshold also reflects the authorities’ effort to balance state budget objectives with facilitating smaller-scale business operations. This can be seen as a necessary step toward enhancing transparency in the business environment and promoting more systematic and sustainable tax compliance.

In this context, HBs and IBs should consider the following key implications and actions:

  • Review revenue and accurately determine tax obligations

HBs and IBs should proactively monitor, record, and control their revenue to determine whether they fall within the VND 500 million threshold. Exceeding this threshold triggers VAT and PIT obligations; therefore, transparent revenue tracking systems are essential to avoid risks of tax reassessment and penalties.

  • Select an appropriate tax calculation method

For those with revenue from over VND 500 million to VND 3 billion, careful consideration should be given to choosing between the deemed tax rate method and the taxable income method. Where input costs are significant and supported by valid documentation, the taxable income method may help optimize tax liabilities.

  • Prepare infrastructure for e-invoices

The mandatory application of e-invoices for HBs with revenue from VND 1 billion requires early implementation of appropriate systems (including tax authority-authenticated e-invoices or cash register-based e-invoices connected to tax systems). Delays in implementation may result in business disruption or compliance risks.

  • Separate and transparently declare business accounts

The requirement to declare bank accounts and e-wallets used for business activities imposes an obligation to ensure transparency in cash flows. HBs and IBs should maintain separate accounts for business and personal purposes to facilitate declaration, reconciliation, and minimize the risk of incomplete revenue assessment by tax authorities.

This milestone not only affirms its outstanding academic capability, but significantly expands the high-quality international education map in the region.

Four international accreditations in 12 months

In Ho Chi Minh City’s international education landscape, authorisation to deliver the International Baccalaureate (IB) programme has long been considered a hallmark of academic excellence. However, attaining the status of a Full IB Continuum School–possessing the capacity to seamlessly implement all three core programmes from Primary Years, Middle Years, to the Diploma Programme–represents a far more rigorous echelon.

This is not merely a matter of adopting a curriculum; it is a profound systemic challenge where everything from educational philosophy and faculty proficiency to operational infrastructure must be harmonised.

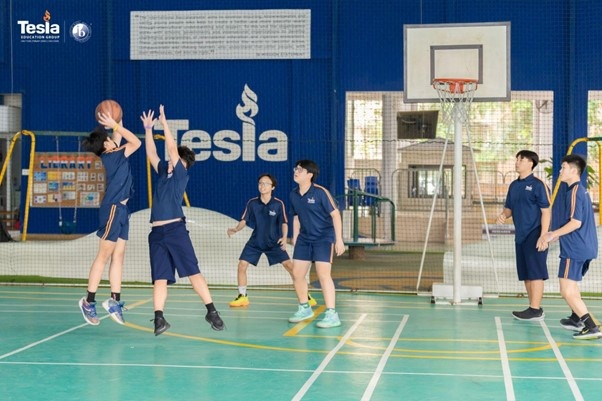
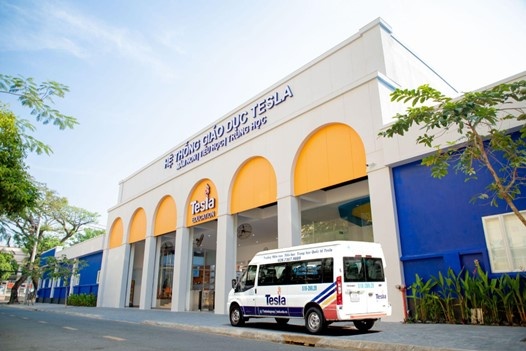
Tesla Education achieves IB Continuum
Tesla Education has become the fifth institution in Ho Chi Minh City authorised to deliver the Full IB Continuum

The official award of the IB Diploma Programme certification in April 2026 marks the culmination of Tesla Education’s five-year standardisation journey. The milestone follows a rapid sequence of international accreditations secured within just 12 months: CIS (June 2025), Cambridge (July 2025), IB MYP (November 2025), and IB DP (April 2026).

This is no coincidence, but the result of a deliberate long-term strategy, underpinned by the consistent adoption and execution of the rigorous standards set by the International Baccalaureate Organisation and other leading global accreditation bodies.

Multi-tiered assurance

In an increasingly fluid world, students must combine a global outlook with the ability to adapt while remaining grounded in local values. Recognising that no single programme can fully deliver this, Tesla Education has developed a mutually reinforcing academic ecosystem, where leading international standards operate in tandem rather than isolation.

The IB Continuum serves as the backbone, shaping mindset and ensuring a coherent learning journey from Kindergarten to Grade 12. Alongside this, the Cambridge programme strengthens subject mastery, providing depth in core disciplines. While the IB is widely recognised for fostering critical thinking, independent inquiry, and global citizenship, Cambridge builds the academic rigour and subject-specific expertise sought by leading universities in the UK and the US.

.

Tesla Education achieves IB Continuum
The Full IB Continuum pathway creates a learning environment where students are not only equipped with knowledge, but also develop intellectual confidence and adaptability

In particular, the integration of the Ministry of Education and Training (MoET) core curriculum within this ecosystem is by no means a “regulatory concession,” but a deliberate, strategic choice. For Vietnamese families, the MoET framework is the anchor that keeps students connected to their mother tongue, history, and national culture. This parallel integration allows students to grow the wings of an international mindset, mastering future skills while retaining their local roots. They can flexibly transition their pathways, fully prepared to step out into the world yet entirely capable of contributing to their homeland.

Strategic location and pioneering financial approach

The introduction of a full IB Continuum at Tesla Education reshapes the decision landscape for parents in Ho Chi Minh City. With most IB Continuum schools clustered in the eastern and southern districts, areas such as Tan Binh, Phu Nhuan, and Binh Tan have lacked fully integrated international pathways. Tesla Education’s campus in Tan Binh helps close this gap, offering a more balanced distribution of access across the city.

Location plays a critical role in the long-term learning experience. Reducing daily travel in increasingly congested traffic can save students one to two hours a day, preserving energy and supporting both wellbeing and participation in extracurricular activities. For many families, this also removes a significant “hidden cost” associated with long commutes.

Tesla Education achieves IB Continuum
From “exclusive” to “accessible”: Tesla Education is expanding access to the International Baccalaureate pathway for Vietnamese families

This advantage is particularly valuable for expatriate communities surrounding Tan Son Nhat Airport. For the large population of South Korean and other expatriates, the demand for an accredited, familiar international curriculum is high. A localised IB Continuum school directly meets this elite demand, sparing families from exhausting cross-city logistics.

Beyond locational leverage, Tesla Education approaches the educational investment pragmatically. With overseas study costing $30,000 to $40,000 annually, a world-class domestic pathway is increasingly attractive. To commemorate the IB Continuum milestone, Tesla has launched a DP Scholarship Fund offering up to 90 per cent tuition coverage for outstanding Grade 10 students.

Reaching up to VND500 million ($19,000), this support makes an elite IB education remarkably accessible. This initiative democratises opportunities, signalling that international education is no longer an exclusive “luxury” but a strategic, long-term investment for modern families.

Ultimately, the synergy of a prime location, a standardised global academic framework, and agile financial policies positions Tesla Education as a masterstroke of strategy. Parents can now holistically optimise both educational quality and their children’s future investment journey.

Established in 2015 in Ho Chi Minh City, Tesla Education is a fully authorised IB Continuum World School, delivering a seamless International Baccalaureate journey from Early Years through High School. The institution pioneers a dual-pathway model that beautifully synergises the Vietnamese national curriculum with the globally renowned IB framework, placing a strong emphasis on science, technology, project-based inquiry, and holistic skill development.

For the current academic year, Tesla is proud to launch the Academic Excellence Scholarship for incoming Grade 10 students. Offering up to 90 per cent tuition coverage–equivalent to a maximum value of VND500 million ($19,000).

Discover more at: tesla.edu.vn

New Zealand institutes strengthen educational exchange and cooperation with Vietnam New Zealand institutes strengthen educational exchange and cooperation with Vietnam

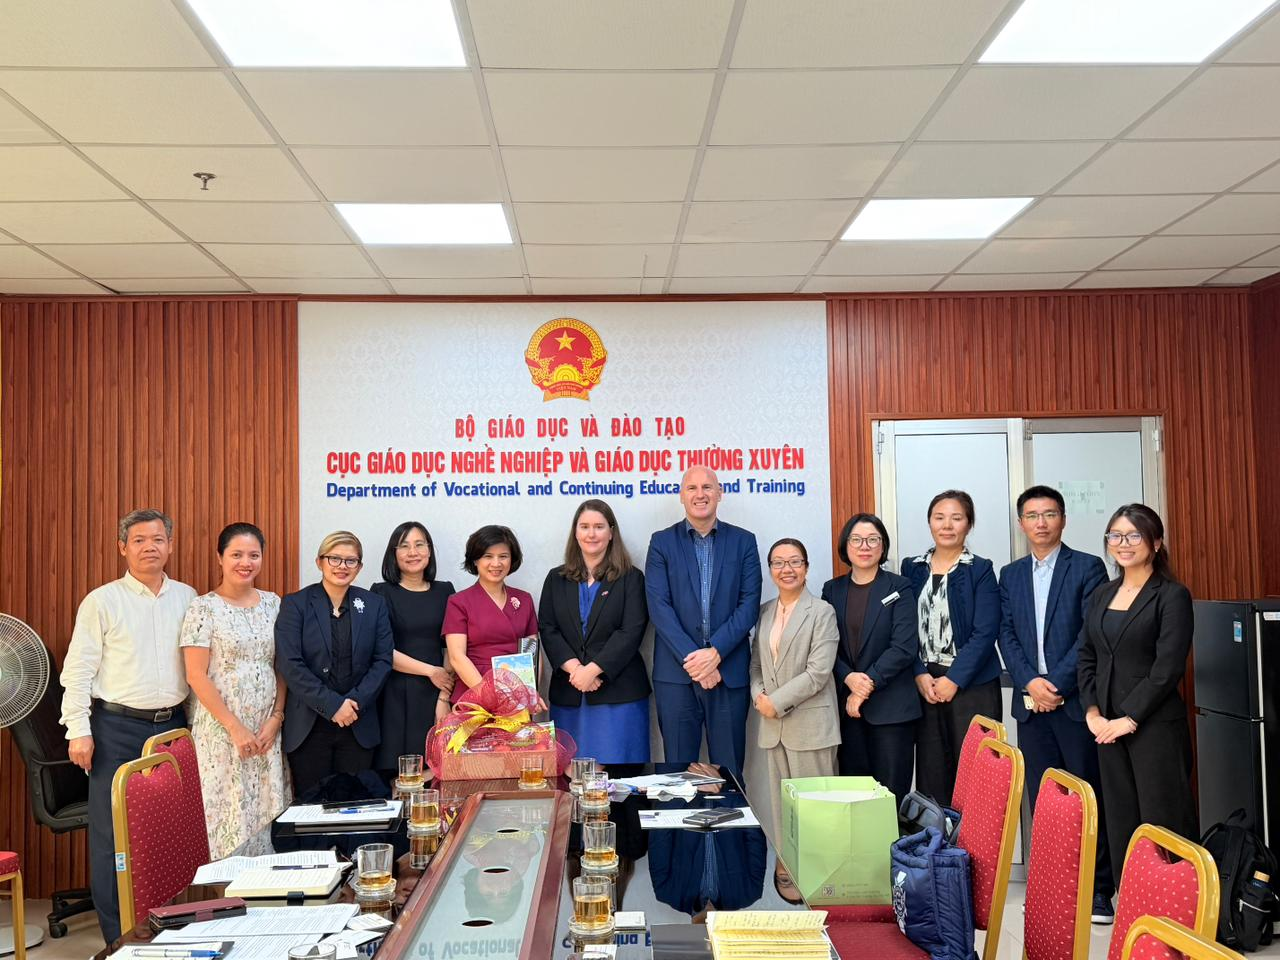
A delegation of New Zealand Institutes of Technology & Polytechnics and Private Training Establishments made its first official visit to Vietnam from March 29 to April 5.

Vietnam and Queensland deepen education ties to power innovation Vietnam and Queensland deepen education ties to power innovation

On April 15, the National Innovation Centre (NIC) under the Ministry of Finance, in collaboration with Trade and Investment Queensland (TIQ), hosted the Education for Innovation Showcase in Hanoi, bringing together around 80 representatives from government agencies, universities, research institutes and businesses across Vietnam and Australia.

ACCA rolls out career workshops for Vietnamese students and teachers ACCA rolls out career workshops for Vietnamese students and teachers

The Association of Chartered Certified Accountants has held a workshop in Hanoi to help operationalise career guidance at school level following new regulatory direction.

On March 31, 2026, the Ministry of Science and Technology of Vietnam issued Circular No. 10/2026/TT-BKHCN, providing detailed guidance on the implementation of certain provisions of the Law on Intellectual Property and Decree No. 65/2023/ND-CP, as amended by Decree No. 15/2026/ND-CP, Decree No. 33/2026/ND-CP, and Decree No. 100/2026/ND-CP.

The Circular sets out detailed procedures relating to industrial property rights, including applications for inventions, industrial designs, layout designs, trademarks, and geographical indications. It also provides guidance on procedures for maintaining, renewing, amending, terminating, or invalidating protection titles, as well as procedures for assignment of industrial property rights.

In addition, the Circular regulates the filing and processing of complaints related to industrial property procedures, rules on authorization and representation, publication in the Industrial Property Official Gazette, recording in the National Register of Industrial Property, industrial property representation services, and the provision of industrial property information.

A notable aspect of the Circular is its detailed guidance on application requirements, filing methods, electronic filings, time-limit calculation, formal examination, substantive examination, publication, opposition, and related procedural matters. These provisions help clarify the practical implementation of Vietnam’s updated intellectual property legal framework.

Overall, Circular No. 10/2026/TT-BKHCN contributes to improving the transparency, consistency, and efficiency of industrial property administration in Vietnam. It is an important reference for individuals, businesses, IP representatives, and organizations involved in the registration, protection, management, and enforcement of industrial property rights.

Download the Full Documents Here

Download the English version here.